November 12, 2026
Agency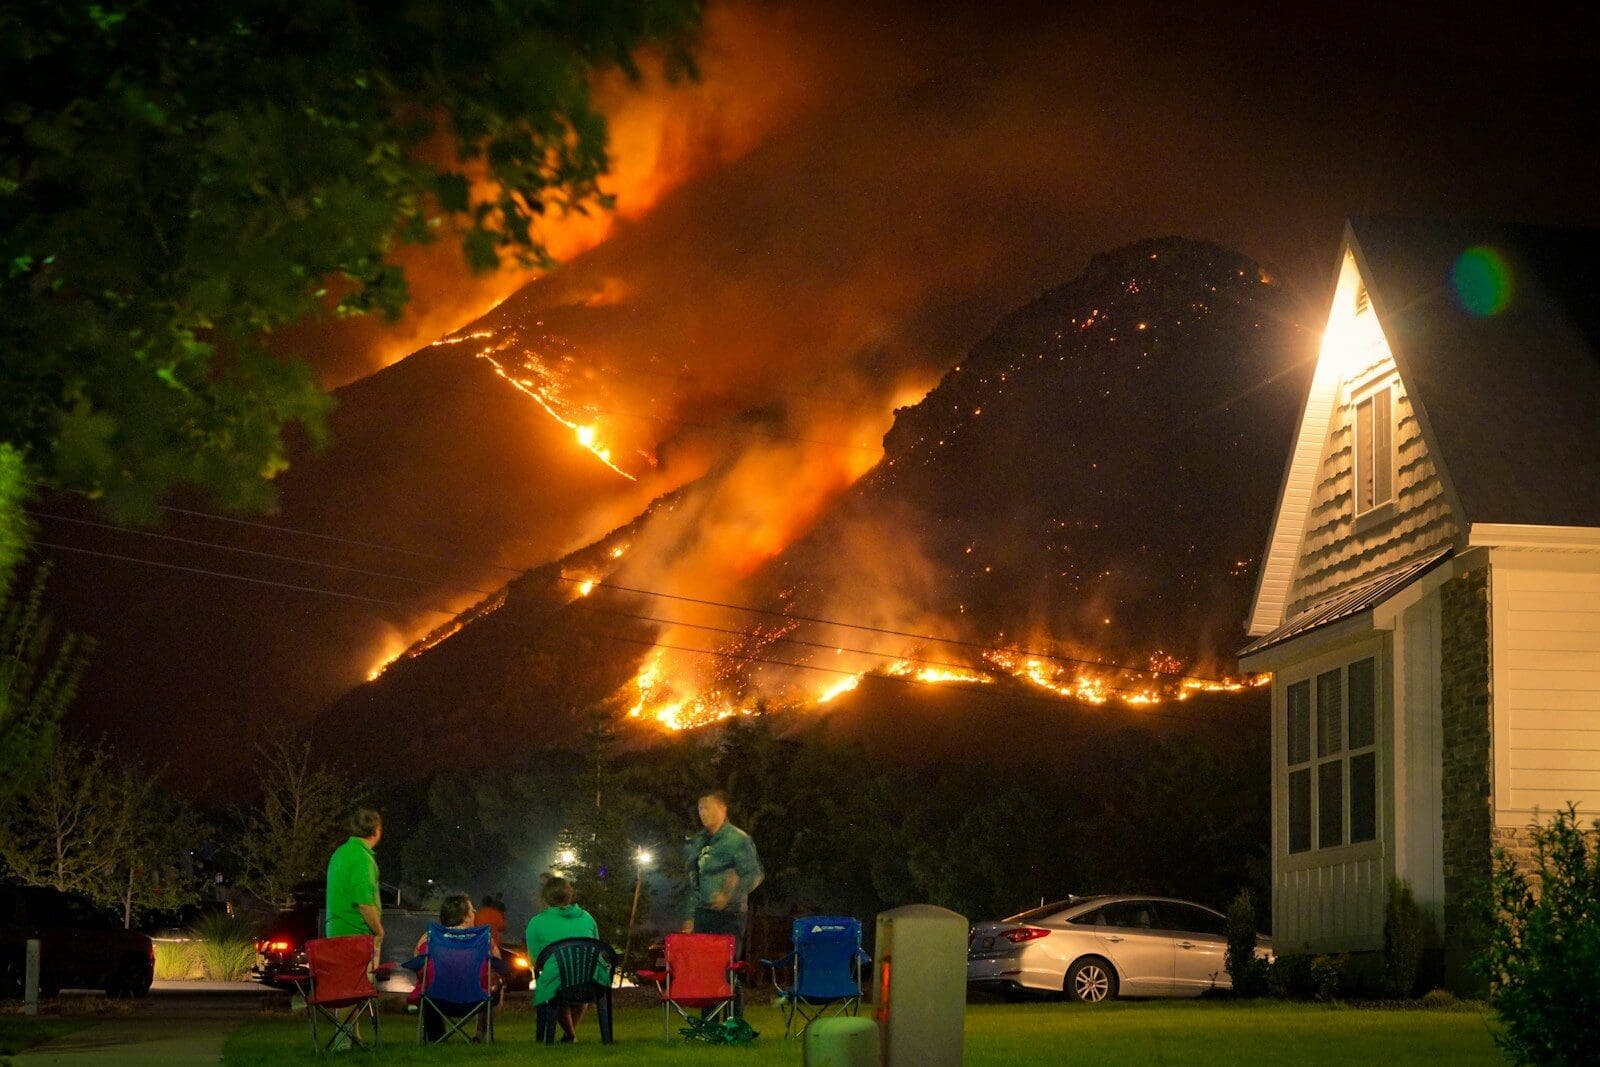
Does Your Ashland Homeowners Policy Cover Smoke Damage From Neighboring Wildfires?
Dry conditions and wildfire activity can create seasonal concerns for homeowners in Ashland, OR. Reinholdt & O'Harra Insurance is here to help clients better understand how homeowners coverage applies to smoke damage, property repair and related claims.
How Does Homeowners Insurance Address Smoke Damage?
Smoke damage from wildfire can be covered by several portions of a homeowners policy. Depending on the policy, coverage may include:
- Dwelling coverage for walls, ceilings and other structural components affected by smoke
- Personal property coverage for damaged belongings
- Other structures coverage for detached garages, fences or outbuildings
- Loss of use coverage if your home becomes temporarily uninhabitable
Coverage details can vary by policy. Some policies require direct physical damage before loss-of-use coverage applies, while others may provide broader coverage.
What Special Considerations Apply to Ashland Homeowners?
Homes near wildfire-prone areas in and around Ashland may face stricter underwriting requirements. Some carriers may limit coverage options in higher-risk areas or impose wildfire-related restrictions, making careful policy comparison worthwhile. Deductibles can also vary, with some policies including a separate deductible for wildfire-related claims.
Is Smoke Damage the Same as Fire Damage Under My Policy?
Coverage for smoke damage may differ from coverage for direct fire damage depending on the policy. In some cases, smoke from a nearby fire may be handled differently than a claim involving fire damage to the property itself. Checking with your agent can help clarify the applicable coverage and claim requirements.
We Can Help Oregon Homeowners
Our team can help you find coverage options that match your budget and priorities. Contact Reinholdt & O'Harra Insurance today to discuss your homeowners insurance needs and get a free personalized quote.
This blog is intended for informational and educational use only. It is not exhaustive and should not be construed as legal advice. Please contact your insurance professional for further information.
Categories: Home Insurance